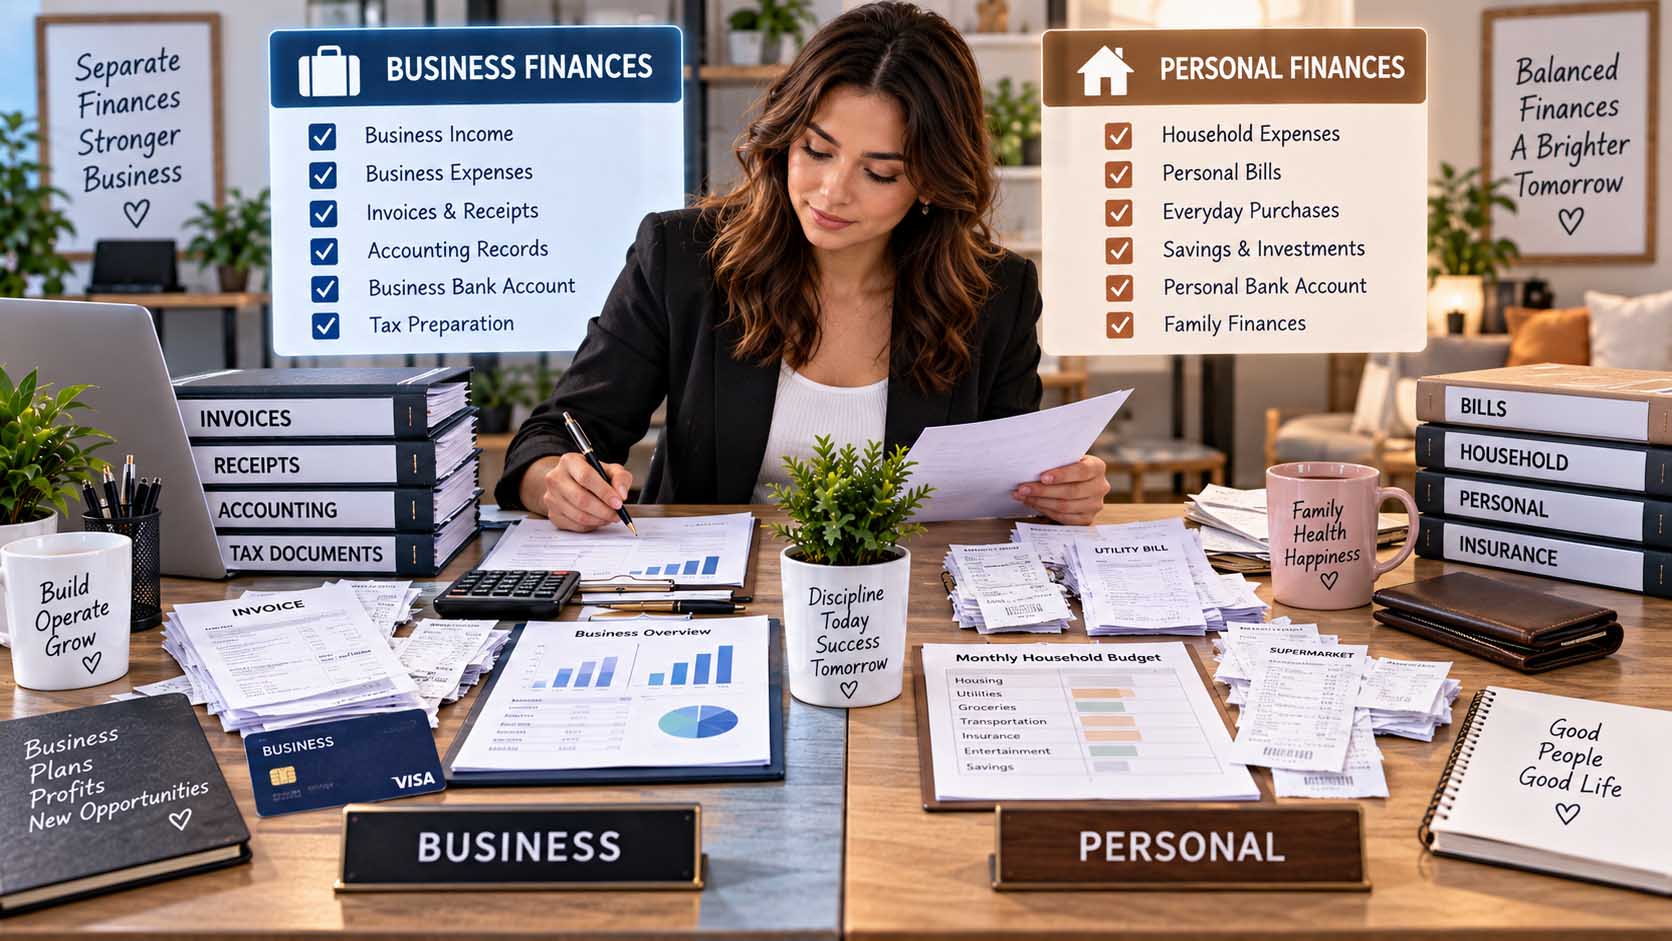
Learning how to separate personal and business finances from day one can make running a small business much easier. When company income and expenses are kept apart from personal spending, owners can see what the business is actually earning, track costs more clearly, and maintain more organized financial records.
Mixing the two may seem convenient when a business is new. However, small transactions can quickly accumulate and make bookkeeping more difficult. Establishing clear financial habits early can prevent unnecessary confusion later.
Why Separate Personal and Business Finances?
The main reason to separate personal and business finances is clarity.
A business account should provide a reasonably clear picture of money coming into and going out of the company. If personal groceries, household bills, entertainment, or other unrelated purchases appear alongside business expenses, that picture becomes harder to understand.
Keeping finances separate can help you:
- Track business income more accurately
- Identify genuine operating expenses
- Simplify bookkeeping
- Organize receipts and financial records
- Review business cash flow more clearly
- Prepare cleaner information for an accountant or tax professional
- Understand how much money is actually available for business needs
The separation also creates a useful financial boundary between the owner’s household spending and the company’s operations.
Open a Dedicated Business Bank Account
One of the simplest ways to separate personal and business finances is to use a dedicated business bank account.
Business revenue can be deposited into that account, while normal business expenses can be paid from it. Personal income and household spending can remain in personal accounts.
This creates a straightforward transaction trail.
For example, suppose a small business receives payments from customers during the month. Those payments go into the business account. Software subscriptions, business supplies, professional services, and other legitimate operating costs are then paid from the same account.
The owner does not need to search through personal transactions to determine which purchases belonged to the company.
The exact banking setup can depend on the business structure and local requirements, so owners should choose an arrangement appropriate for their circumstances.
Use a Separate Business Payment Card
A dedicated business debit or credit card can provide another layer of separation.
Instead of using a personal card whenever the business needs supplies or services, the owner can use the designated business payment method for company purchases.
This makes transaction reviews easier because the card activity is already associated with business spending.
It also reduces the number of transactions that need to be sorted manually during bookkeeping.
The important part is establishing a clear rule: the business card is for approved business purchases, while personal spending stays on personal payment methods.
Keep Business Expenses and Personal Purchases Distinct
Separating accounts is only useful if spending habits follow the same boundary.
Business expenses can include items such as:
- Business software
- Office supplies
- Equipment
- Advertising
- Professional services
- Business-related travel
- Other costs directly connected with operating the company
Personal spending should remain outside the business records.
For example, buying a laptop that is genuinely used for company operations may be a business-related purchase, while buying household groceries is a personal expense. The correct treatment of expenses can depend on the circumstances and applicable accounting or tax rules.
When there is uncertainty, keeping the receipt and asking a qualified professional is safer than automatically classifying the transaction.
What If You Accidentally Use Personal Money for the Business?
Even with good systems, mistakes happen.
A business owner may accidentally purchase a business item with a personal card. Another owner may temporarily use personal funds to cover a company expense.
The important thing is not to ignore the transaction.
Keep the receipt and record the transaction properly according to the business’s bookkeeping system. Depending on the business structure, the transaction may need to be treated as an owner contribution, reimbursement, or another type of entry.
Likewise, if business funds are used for a personal purchase, the transaction should not simply be left in the records as an ordinary business expense.
Consistent documentation makes these situations much easier to handle.
Establish a Clear Process for Paying Yourself
Business owners also need a defined way to move money from the company to themselves.
Rather than transferring money randomly whenever personal spending is needed, establish a consistent process appropriate for the business structure.
The correct approach can differ between a sole proprietorship, partnership, corporation, or other structure. Accounting and tax treatment can also vary.
The key principle is that money moving between the business and the owner should be identifiable and recorded correctly.
That distinction helps prevent owner-related transactions from being confused with normal operating expenses.
Keep Receipts and Records Organized
Good financial separation depends on good records.
Create a simple system for storing business receipts, invoices, payment records, and other financial documents. Digital storage can make organization easier, but the specific system matters less than consistency.
A useful routine might include:
- Save the receipt when a business purchase is made.
- Record the transaction in the bookkeeping system.
- Assign an appropriate category.
- Review the transaction against the bank or card statement.
- Keep supporting documentation together.
Regular organization is easier than trying to reconstruct months of transactions later.
Review Your Business Finances Regularly
Separating accounts does not eliminate the need for financial reviews.
Set aside time regularly to examine business income, expenses, outstanding payments, account balances, and unusual transactions.
During the review, look for personal purchases that may have accidentally been charged to the business account. Also check whether business expenses were paid personally and need to be recorded.
These reviews can help maintain the separation and identify small problems before they become larger bookkeeping tasks.
For owners building a broader system for managing business operations, cash flow, records, and financial organization, these details can be considered alongside the practical steps involved in running a company.
What Should You Do If Your Finances Are Already Mixed?
If personal and business finances have already been mixed, do not assume the situation cannot be fixed.
Start by establishing separate accounts and payment methods. Then review existing transactions and identify which ones were business-related, personal, owner-related, or unclear.
Keep supporting documentation for transactions that need clarification.
If the records cover a significant period or contain complicated transactions, working with an accountant or qualified bookkeeping professional can help determine how they should be organized.
Once the existing records are cleaned up, the focus can shift toward maintaining the new system consistently.
Make Financial Separation a Daily Business Habit
Separating personal and business finances does not require an elaborate system. It requires clear boundaries and consistent habits.
Use dedicated accounts, keep business purchases on business payment methods, save receipts, record owner transactions correctly, and review financial activity regularly.
Starting these practices from day one can prevent many avoidable bookkeeping problems as the business grows. More importantly, it gives the owner a clearer view of the company’s financial activity and makes everyday money management easier to understand.
The earlier the separation becomes part of normal business operations, the easier it is to maintain over time.